FOMO in the financial markets
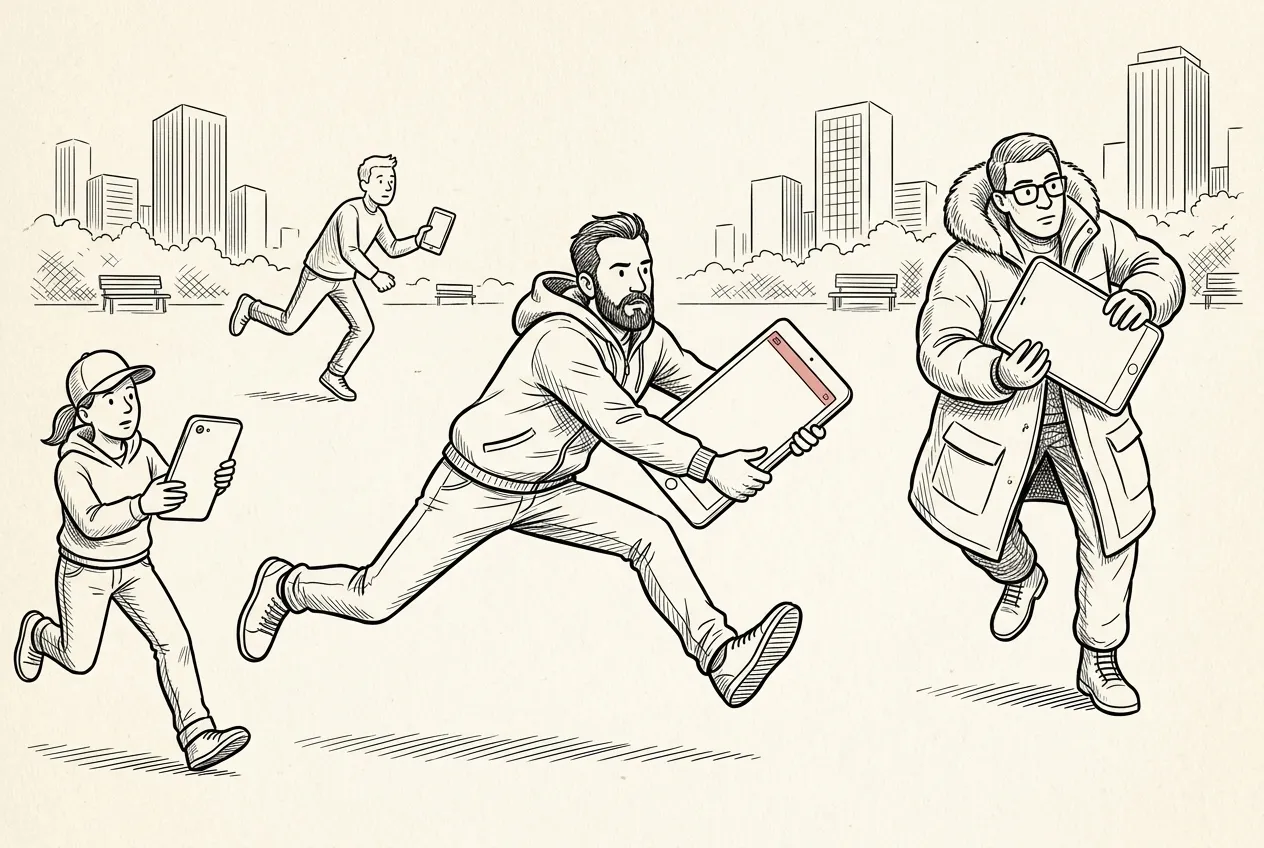
The phenomenon of ‘pump and dump’ in the financial markets has once again regularly been in the news: “Investors lost billions of dollars in July betting on a handful of small US-listed Chinese stocks that plunged in value shortly after being heavily promoted on social media”.[1] ‘Pump and dump’ involves a person or company, or a group of persons or companies, promoting a share or another financial instrument through various channels in order to drive up its price. That is the ‘pump’ part of the manipulation. The channels may consist of online forums, but nowadays far greater use is also made of cross-media strategies. The marketing may run through a combination of social and traditional media, such asWhatsApp, Snapchat and YouTube. As soon as the price of the share or financial instrument has been pushed to a higher level because the ‘pump marketing’ has prompted retail investors in particular to buy, the consortium that organised the ‘pump and dump’ will sell the shares or other financial instruments it holds at the higher price. The manipulating consortium thereby obtains an improper advantage, and this advantage comes at the expense of the retail investors, who shortly afterwards will see the price fall and part of their assets evaporate. The reverse is, of course, also possible: a ‘pump and dump’ aimed at first driving the price down, then buying, and waiting for the price to rise again. This is sometimes referred to as ‘trash and cash’.
From a theoretical perspective, ‘pump and dump’ drives the price of a financial instrument away from its fundamental value. During the period in which there is a delta between the price and the fundamental value, the manipulating consortium can thereby obtain an advantage.As soon as the market discovers that air has been blown into the price, that air will slowly leak out of it, and the opportunity for the consortium to obtain any further advantage disappears. This form of manipulation in the financial markets is very old. Isaac le Maire, together with a consortium, is believed to have manipulated the share price around 1609 by spreading negative rumours.[2]In my view, there are several causes for the renewed interest. First, the threshold for publishing news has been lowered by the aforementioned social and traditional media, which have contributed to the democratisation of news.Second, AI tools make it easier for messages to be drafted and sent that are specifically timed and targeted. Third, the population of retail investors is also constantly in flux, and there are periods in which investing in financial and crypto markets is popular among a younger generation. Fourth, changes in the internal organisation of some exchanges, through the admission of more penny stocks, have made them more susceptible to manipulation.
The first three causes relate to the existence of more accessible and inexpensive means of communication that the manipulating consortium can deploy to win the trust of retail investors, as well as to the susceptibility of the recipients of the information to such messages.
The fourth cause concerns the internal organisation and infrastructure of exchanges. For instance, in the UnitedStates a relatively large number of small Chinese companies have obtained a listing on Nasdaq. “Many scams are linked to the record number of Chinese companies that went public onUS exchanges in 2024, a trend that has continued this year with China and HongKong-based companies dominating US micro cap IPOs.”[3]
Nasdaq and the US authorities immediately took measures to curb ‘pump and dump’ involving shares in small Chinese companies. Nasdaq has amended its listing requirements: “Nasdaq has said it will tighten listing rules and trading standards for small stocks as it seeks to combat a spate of suspected“pump and dump” scams involving Chinese companies listed in the US.”[4]The US authorities, in this case the Securities andExchange Commission (SEC), also intend to tackle the infrastructure, in this case the facilitators. This concerns a group of small underwriters, auditor sand law firms. “[Regulators]are going to crucify the bulge bracket,” said a person familiar with the SEC’s thinking, referring to the small white-collar groups that act as a “conduit”for Chinese companies applying to list in the US, as opposed to the so-called bulge bracket of prestigious banks and law firms. “This is a national security issue, that’s what the SEC’s focus is,” the person added.”[5]
It would be advisable for the EuropeanSecurities and Markets Authority (ESMA) to monitor whether similar risks of ‘pump and dump’ involving foreign penny stocks may arise in the European Union(whether or not as a result of a possible waterbed effect of enforcement in theUnited States) and which measures would be appropriate. With regard to ‘pump and dump’ in crypto markets, national supervisors are already active. On 26September 2024, the Dutch Authority for the Financial Markets (AFM) issued a warning entitled: “AFM warns against pump and dump with crypto.”[6]This warning was issued because, as of 30 December 2024, market manipulation in crypto markets is prohibited under MiCAR[7].
The resilience of financial markets against ‘pump and dump’ does not depend solely on regulation and enforcement. It is also important that investors, and especially retail investors, remain aware of the risks. This may also help to dampen FOMO-driven hypes to some extent in advance. Ultimately, what matters is that retail investors understand how investing works, what risks it entails, and that rapid day trading in penny stocks or crypto-assets may yield a high daily profit, but also a large daily loss. I conclude with a fitting quotation from De la Vega’s classic work of 1688: “The first principle [in speculation]: Never give anyone the advice to buy or sell shares, because, where perspicacity is weakened, the most benevolent piece of advice can turn out badly. The second principle: Take every gain without showing remorse about missed profits, because an eel may escape sooner than you think.It is wise to enjoy that which is possible without hoping for the continuance of a favorable conjuncture and the persistence of good luck. The third principle: Profits on the exchange are the treasures of goblins. At one time they may be carbuncle stones, then coals, then diamonds, then flint-stones, then morning dew, then tears. The fourth principle: Whoever wishes to win in this game must have patience and money, since the values are so little constant and the rumors so little founded on truth.”[8]
This blog is an adapted article from: FOMO in the financial markets, Tijdschrift voor Bijzonder Strafrecht en Handhaving, https://doi.org/10.5553/TBSenH/229567002025011006001. Originally published 2025; updated October 2026
Matthijs Nelemans is Professor of Financial Law Enforcement at Tilburg Law School and founder of Neemley.
[1] G. Steer, ‘Investors lose billions on penny stocks after “pump and dump” scams multiply’, Financial Times, 19 August2025.
[2] L.O. Petram, The world’s first stockexchange: how the Amsterdam market for Dutch East India Company shares became amodern securities market, 1602-1700 (PhD thesis), University of Amsterdam2011, pp. 24-25.
[3] G. Steer, ‘Nasdaq to tighten rules on small stocks after suspected “pump and dump” scams’, Financial Times, 4September 2025.
[4] Ibid,
[5] Ibid.
[6] AFM press release of 26 September 2024, ‘AFM waarschuwt voor pump en dump met crypto’s’ (available in Dutch at https://www.afm.nl/nl-nl/sector/actueel/2024/september/pump-en-dump).
[7] Regulation (EU) 2023/1114 of the European Parliament and of theCouncil of 31 May 2023 on markets in crypto-assets, and amending Regulations(EU) No 1093/2010 and (EU) No 1095/2010 and Directives 2013/36/EU and (EU)2019/1937.
[8] H. Kellenbenz (ed. & trans.), Confusion de Confusiones by Joseph de la Vega 1688: Portions Descriptive of the AmsterdamStock Exchange, Cambridge: Harvard University Press 1957, p. 10.
Recommended Articles
Subscribe to receive new posts